 CashKasama
Detailed information
Detailed review
The lightning-fast disbursement of funds through e-wallets has always been a major draw for consumers in the Philippines facing urgent financial needs. However, the price of this convenience often comes with hefty costs. CashKasama short-term unsecured lending model clearly reflects this reality: although it has a clear legal status, the app still operates by deducting high service fees and significantly shortening the actual repayment period for borrowers. The following sections examine its legal registration, actual borrowing process, and potential cost traps that users need to consider carefully.
Is CashKasama Trustworthy? Checking Its SEC Registration
For first-time users, CashKasama operates as a financial app that specialises in providing short-term unsecured loans to people who do not want to go through the complicated assessment process required by traditional banks. The first key question concerns the app’s legality. Unlike unregistered loan-sharking apps operating without proper oversight, this platform has transparent registration records under the Philippine Securities and Exchange Commission (SEC).
Operating company: SURE MONEY LENDING INVESTORS INC.
Company Registration No.: SEC Registration No. CS201907919
Certificate of Authority No.: Certificate of Authority (CA) No. 2976
Head office address: Sitio, Kamangahan, Barangay Labogon, Mandaue, Cebu, Philippines
Having an SEC licence demonstrates that this is a legally operating business, helping borrowers avoid the risk of losing money to scams involving upfront deposits. However, this legal status only confirms compliance with business regulations; it does not mean that borrowing costs are low.
How to Apply for a CashKasama Loan Through GCash or Maya
The application process is fully automated, allowing users to complete it within 10 minutes. To qualify, you must be a Filipino citizen aged 18 to 60, have a stable job, and possess at least one valid government-issued ID, such as a UMID, SSS ID, Driver’s License, or Passport.
The steps in the app are as follows:
Download the App and Activate Your Account: Download the CashKasama app from the app store, enter your phone number, and receive an OTP to activate your account.
Complete Your Application: Provide your personal information and income level, then upload a photo of your valid ID.
Receive Your Loan: Choose a disbursement method, such as an e-wallet like GCash or Maya, or a bank account, so the system can automatically release the funds once your application is approved.
However, users should pay attention to data security. The system requires access to the Camera and Photo Library so that its AI can compare a real-time selfie with the submitted ID. Granting these permissions carries a risk of personal information being leaked if borrowers fail to settle their loans on time.
CashKasama Interest Rates, Hidden Fees, and Penalties
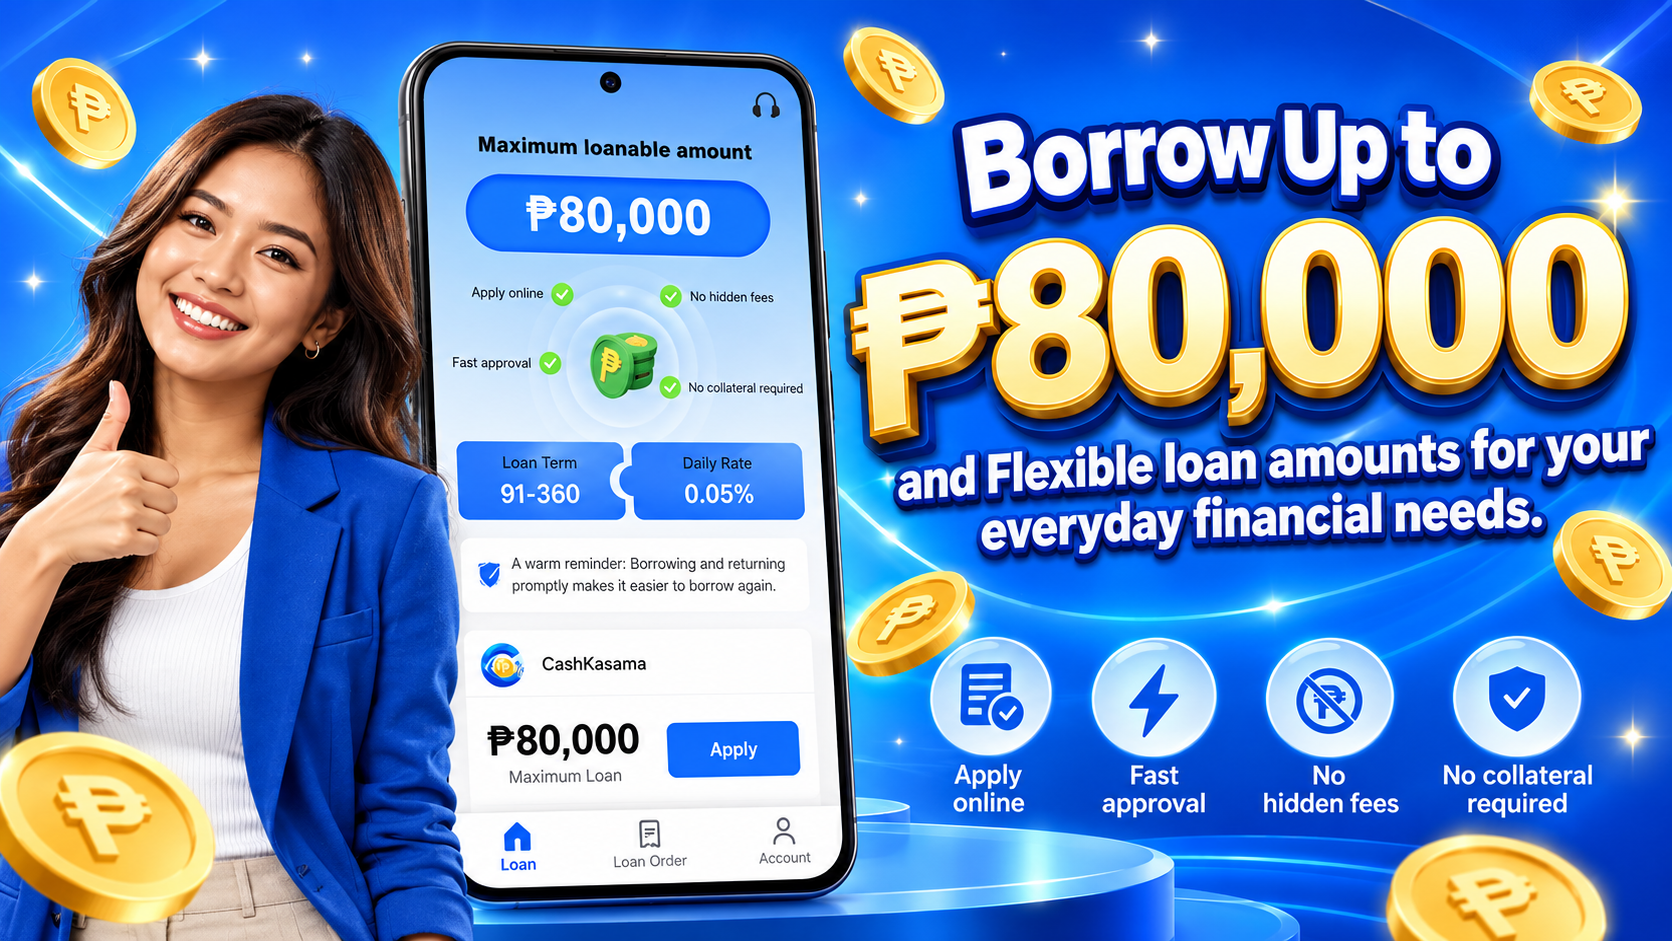
The gap between marketing claims and actual user experiences is the most important factor borrowers need to understand to avoid falling into financial difficulties. In its promotional materials, the service advertises a maximum interest rate of 30% per year, with flexible loan terms ranging from 91 to 365 days. In practice, however, users may experience a different scenario:
Actual repayment periods are significantly shorter: For new accounts or first-time loans, users are often approved for terms of only 7 to 14 days instead of the several months or one year advertised.
Hidden fees deducted directly from the loan: To maximise profits while remaining within the interest rate cap, the app automatically deducts service fees ranging from 15% to 25% as soon as the loan is approved.
Practical example: When applying for a ₱4,000 loan, a 20% deduction for platform and service fees, equivalent to ₱800, means that you receive only ₱3,200 in your GCash wallet. Although you receive a smaller amount, after 7 to 14 days, the principal you must repay remains ₱4,000, plus the interest incurred. This pushes the cost of borrowing to a very high level.
Late Payment Penalties
In addition, late payment penalties can become a significant financial burden. Even if you are just 1 day late, the system will impose a fixed penalty fee plus accumulated penalty interest ranging from 2% to 5% per day, calculated on the total outstanding balance. As a result, the total debt could increase to one and a half or even twice its original amount after just 5 to 7 days of delay.
Consequences of Bad Debt and Safe Payment Methods
When faced with high borrowing costs, some users may consider not repaying their loans. However, this decision comes with serious legal and credit consequences:
High-pressure debt collection: Although the SEC has rules prohibiting threatening behaviour, debt collection agents associated with the app may still make repeated calls and send continuous messages to pressure borrowers, as well as the reference contacts they provided.
Risk of being blacklisted for bad debt nationwide: Unlike loan-sharking apps, CashKasama is a formally registered organisation with the right to report bad debt records to the CIC (Credit Information Corporation). Once your bad debt is recorded in the national system, you will be placed on a blacklist and lose access to credit from any bank or major financial institution in the Philippines.
For safer payment methods, users should pay directly through the app by linking their GCash or Maya wallet, or through partner payment centres such as 7-Eleven, where they can receive an immediate payment confirmation receipt. Never transfer money to personal account numbers belonging to people claiming to be company employees.
Summary
Overall, CashKasama stands out for its convenience, fast application process, and transparent legal status with the regulatory authority. However, its main drawbacks are the short actual repayment periods and exorbitant service fees. Users should only consider using this service when facing a genuinely urgent situation in the Philippines and when they are 100% certain that they will have a source of income to settle the loan within one week. Absolutely avoid taking out a new loan from this app to repay debts owed to other platforms, as this can lead to a prolonged cycle of debt.
💬 Q&A & Discussion
Ask questions and share your experiences with " CashKasama " with the community.
💬 Log in to create a new topic and share experiences
No topics yet.