 BaryaGo
Detailed information
Detailed review
Getting a loan through an app allows users in the Philippines to access funds quickly without visiting a bank. However, fast disbursement also comes with concerns about borrowing costs and debt collection practices. BaryaGo loan app is one of the names receiving considerable search interest, with most questions focusing on its SEC registration status and the risks borrowers may face. Evaluating this platform requires looking at the operating company, disbursement process, fees, and reports concerning its debt collection activities.
What Is BaryaGo Loan App? An Overview of the Platform
BaryaGo provides unsecured online lending services and operates primarily on the Android operating system. Users can register an account using their mobile phone number and upload government-issued identification documents from the Philippines, such as UMID, SSS, PRC, or Driver’s License, to complete their application.
The app uses an internal credit scoring algorithm to automatically assess loan applications. Once an application is approved, the funds are transferred directly to the borrower’s bank account or popular e-wallets in the Philippines, including GCash and Maya.
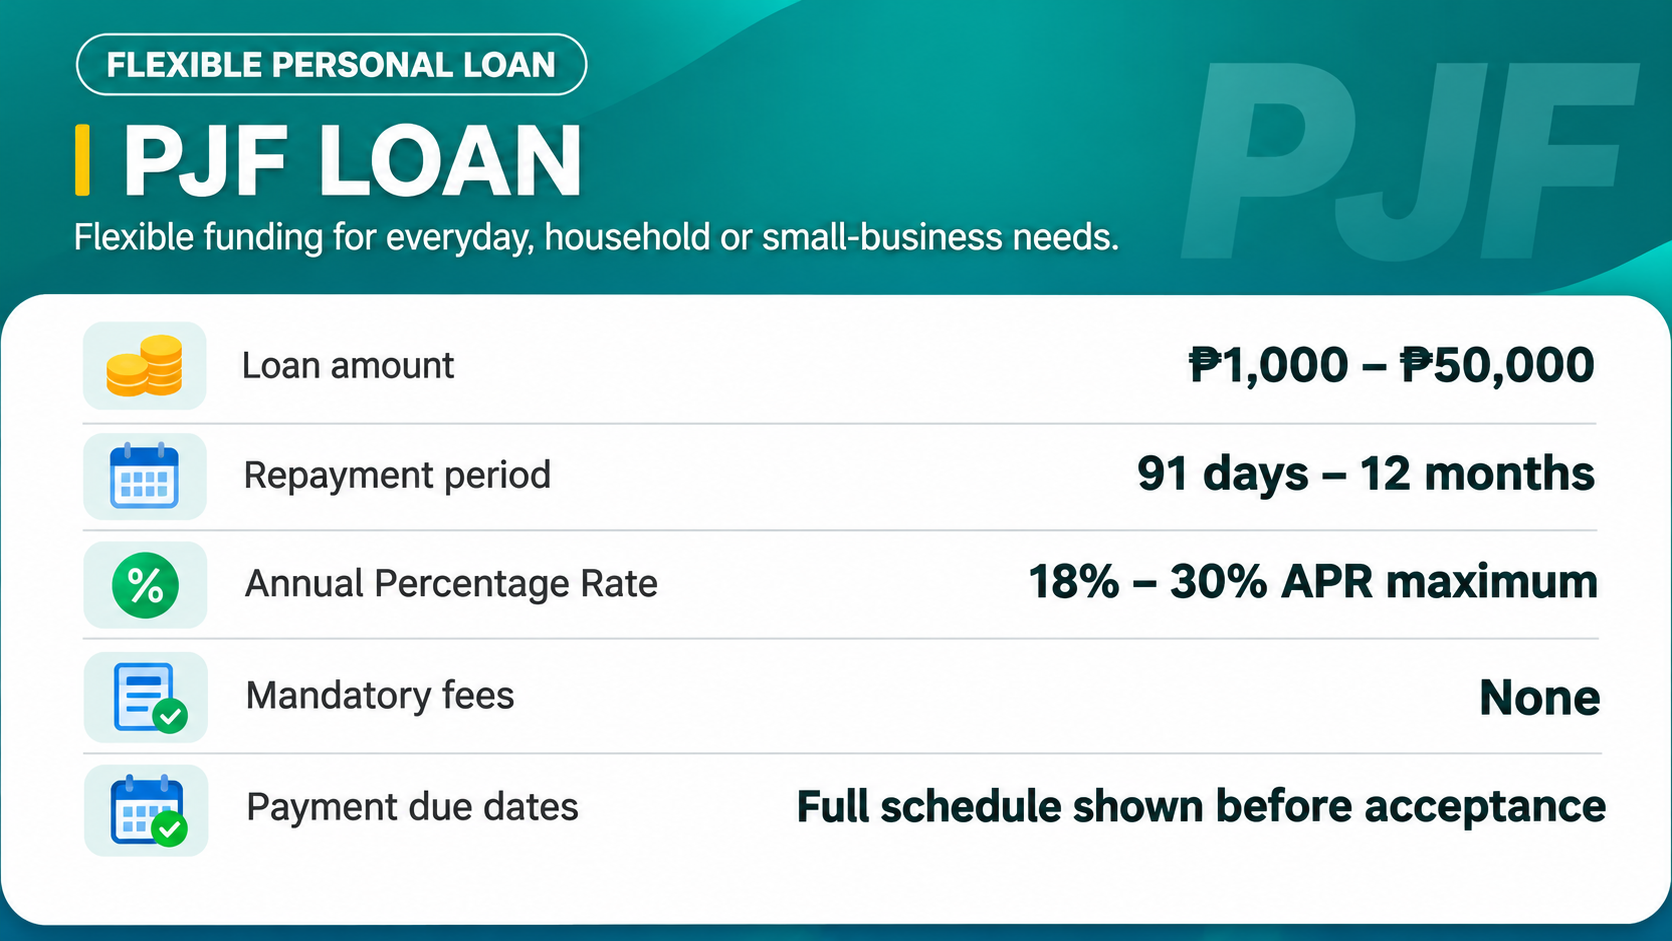
The company directly operating the app and bearing legal responsibility for it is PJF LENDING INC. According to the company’s official privacy policy, BaryaGo collects personal information to verify users’ identities and assess their ability to repay loans.
Is BaryaGo Registered with the SEC?
In terms of its legal status, BaryaGo’s parent company, PJF LENDING INC., has been issued company registration number CS201917524 and a Certificate of Authority (CA) No. 3143 by the Securities and Exchange Commission of the Philippines (SEC).
The company’s registered office address is:
303 Unsang Street Barangay Dirita-Baloguen, Iba, Zambales, 2201 Philippines.
However, having a financial operating license does not automatically mean that every app under the company’s network has been reviewed by the SEC or properly included in its official list of regulated platforms. The SEC has repeatedly issued warnings about financing companies that are legally registered but still operate online lending platforms (OLPs) that have not undergone review or been officially updated in its records.
Borrowers should therefore distinguish between the parent company’s CA and each individual app’s compliance status. Holding a CA does not necessarily mean that all lending activities, interest charges, and debt collection practices of related apps comply with the regulations issued by the Bangko Sentral ng Pilipinas (BSP).
A Closer Look at the Benefits and Risks of Borrowing from BaryaGo
Advertised Benefits
BaryaGo focuses on an online application process and promotes several features:
- Minimal requirements: Borrowers are not required to submit payslips as proof of income or provide collateral.
- Fast disbursement: The advertised processing time from application to receiving the funds is around 15 to 30 minutes.
- High approval rate: The platform targets people who do not qualify for financing from traditional banks.
Fast processing and simple application requirements may allow borrowers to receive funds within a short period. However, users should also consider the fees they will have to pay and the accompanying loan conditions rather than focusing solely on disbursement speed.
Hidden Lending Traps and Actual Risks
Service Fees May Take Up a Large Portion of the Loan
Despite advertising low interest rates, BaryaGo may directly deduct a fee described as a service fee or management fee when disbursing the loan. The stated fee ranges from 25% to 40% of the loan amount.
For example, if you apply for a 5,000 PHP loan, the actual amount you receive may be only 3,200 PHP. Despite not receiving the full amount you applied for, you are still required to repay 5,000 PHP plus interest when the loan falls due.
Repayment Terms May Be Shorter Than Expected
The information displayed during the application process may lead borrowers to believe that the loan runs for several months. However, the actual repayment period is often shortened to just 7 days. With such a short repayment window, borrowers may face repayment pressure almost immediately after receiving the funds.
The App Requests Extensive Access to Device Permissions
Immediately after installation, BaryaGo requests access to the phone’s contacts, real-time location, SMS messages, and personal photo gallery. These permissions are directly related to users’ private information.
Does BaryaGo Engage in Harassment and Public Shaming on Facebook?
In consumer protection communities such as Stop Online Loansharks Philippines, BaryaGo and other apps under the “PJF Loan” group have repeatedly faced reports concerning improper debt collection practices.
According to these reports, when borrowers are late with payments by even just a few hours, debt collection activities may escalate into psychological pressure tactics, including:
- Calling and messaging people in the borrower’s contact list: Collection agents use previously collected contact information to reach out to borrowers’ relatives, friends, and colleagues in large numbers, intending to put pressure on borrowers and damage their reputation.
- Posting personal information on Facebook: Some reports mention the creation of fake Facebook accounts, which are then used to post borrowers’ profile photos and government-issued IDs in public groups or send them directly to people on their friends lists.
- Using fake legal notices: Borrowers may receive documents bearing forged seals and impersonating court notices of legal action or summonses from Barangay authorities to frighten them.
These are the types of activities reported by consumers in connection with BaryaGo and the PJF Loan group of apps.
What to Do If Apps Under PJF Loan Keep Harassing You
If you or a family member experience intimidating debt collection practices from BaryaGo, you can take the following steps to limit further harassment and preserve evidence.
1. Revoke the App’s Access Permissions
Open Settings on your phone, select Apps, find BaryaGo, and disable its access to Contacts, Photos, and Location. After that, uninstall the app.
2. Strengthen Your Social Media Privacy Settings
Switch your personal Facebook account to private, restrict messages from strangers, and hide your friends list. These steps can limit collection agents’ ability to access information about your relatives and personal connections.
3. Keep All Available Evidence
Take screenshots of threatening messages, record intimidating collection calls, and save posts that attempt to damage your reputation. These materials may be used when submitting a complaint or filing a formal report.
4. File a Complaint with the Relevant Authorities
- Submit a complaint together with supporting evidence through the SEC iMessage Portal, the complaint platform of the Securities and Exchange Commission of the Philippines.
- Contact the National Bureau of Investigation (NBI) or the Philippine National Police Anti-Cybercrime Group (PNP-ACG) to seek legal intervention if your personal safety is threatened.
Conclusion
BaryaGo raises several concerns regarding borrowing costs, personal privacy, and debt collection practices. Although its online application process and fast disbursement may appeal to people who urgently need money, borrowers should carefully review their repayment obligations before applying. Do not let an immediate financial need expose you to prolonged pressure and difficulties later on.
💬 Q&A & Discussion
Ask questions and share your experiences with " BaryaGo " with the community.
💬 Log in to create a new topic and share experiences
No topics yet.